

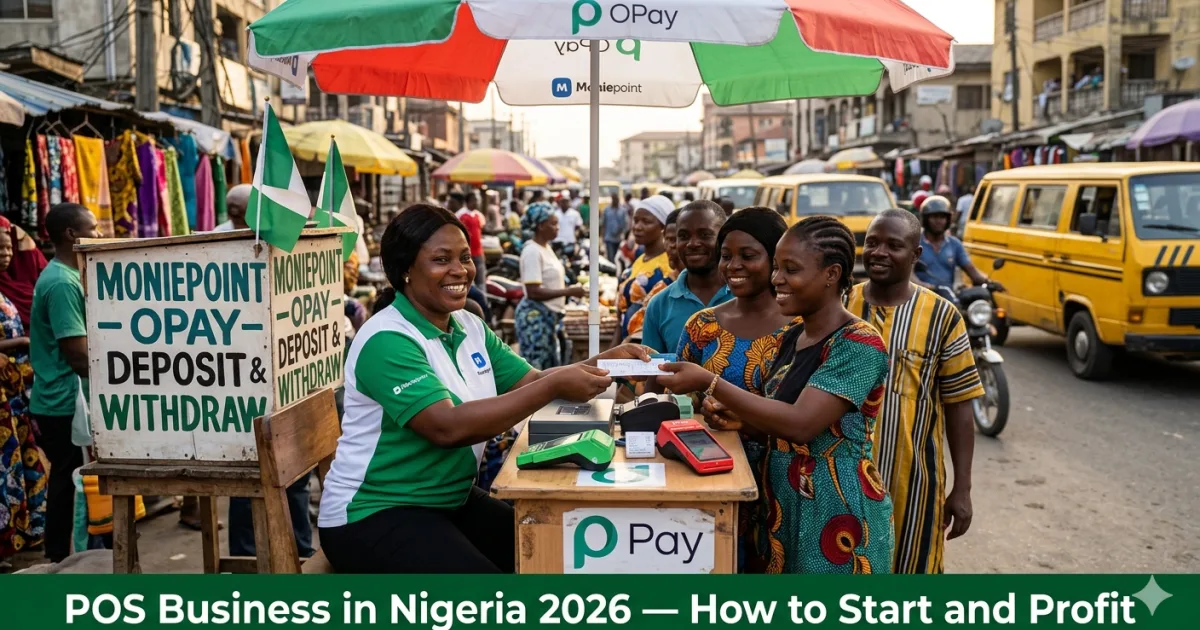
📌 Quick answer (checked 18 October 2026): You can still start a POS business in Nigeria in 2026, but the rules are stricter than before. Since 1 April 2026 the Central Bank of Nigeria (CBN) requires every agent to work with only one bank, fintech or super-agent, and all agent transactions must run through one dedicated agent wallet. Cash-outs are capped at ₦100,000 per customer per day and ₦1.2 million per agent per day. Each terminal must be geo-fenced to your registered location, and the operating radius was widened to 70 metres, with enforcement from 1 August 2026. Terminal prices and fees change often, so get the current quote from your provider’s app or relationship officer before you pay anything.
POS stands are everywhere in Nigeria, from market gates in Onitsha to junctions in rural Benue, and they handle a huge amount of money. Figures from the Nigeria Inter-Bank Settlement System (NIBSS), compiled by Financial Derivatives Company and published in April 2026, put PoS transactions at ₦18.78 trillion in the first quarter of 2026. That is 79.03% more than the ₦10.49 trillion recorded in Q1 2025.
The business has also changed a lot since late 2025. The CBN’s new agent banking guidelines, geo-fencing and new cash withdrawal limits all affect how you set up, which provider you choose and how much cash you can pay out each day. This guide covers the rules in force today, what you need to start, how to register, and how to work out whether your spot will make money.
The CBN rules every POS agent must follow in 2026
The CBN issued revised Guidelines for the Regulation of Agent Banking on 6 October 2025 and gave the industry until 1 April 2026 to comply. TechCabal, BusinessDay and Nairametrics all reported the main points:
| Rule | What it means for you | In force from |
|---|---|---|
| One principal only | You can work with just one bank, microfinance bank, payment service bank, mobile money operator or licensed super agent. Running Moniepoint, OPay and PalmPay terminals side by side is no longer allowed. | 1 April 2026 |
| Dedicated agent wallet | Every agent transaction must go through one dedicated agent account or wallet with your principal. Transactions outside it can lead to termination or blacklisting. | 1 April 2026 |
| Cash-out limits | ₦100,000 per customer per day and ₦500,000 per customer per week. Your terminal’s total cash-out is capped at ₦1.2 million a day. | Per-customer limit since 17 December 2024; carried into the 2025 guidelines |
| Deposits and bill payments | ₦100,000 per transaction per day and ₦500,000 per week, as reported by BusinessDay. | 1 April 2026 |
| Geo-fencing | Your terminal is tied to the GPS coordinates of your registered location and can only work within 70 metres of it (the limit was 10 metres before). | Enforcement from 1 August 2026 |
| Receipts and signage | You must give a receipt for every transaction and display your principal’s name, the approved charges and contact numbers. | 1 April 2026 |
| Training | You must complete training twice a year on KYC, fraud prevention, customer service and financial literacy. | 1 April 2026 |
| Relocation | You cannot move, transfer or close your location without your principal’s approval, usually with at least 30 days’ written notice. | 1 April 2026 |
BusinessDay reported that the guidelines set fines of ₦2 million to ₦20 million for breaches such as false reporting or branding violations. Those fines are aimed mainly at principals and super agents. As an individual agent, the real risk is that your principal switches off your terminal or ends your contract.
Weekly cash limits for your customers
The CBN’s revised cash policy took effect on 1 January 2026, as reported by Channels TV and The ICIR. It removed limits on cash deposits and set a cumulative weekly cash withdrawal limit of ₦500,000 for individuals and ₦5 million for companies. The limit covers all channels together, including ATMs, POS and over-the-counter withdrawals. Anything above it attracts a fee of 3% for individuals and 5% for companies. If a customer says their bank declined a POS withdrawal, they may have used up their weekly limit somewhere else.
Network and terminal rules
Every terminal must be registered with a Payment Terminal Service Aggregator (NIBSS or Unified Payment Services Ltd) with accurate GPS coordinates. A CBN circular dated 11 December 2025 also requires acquirers to stay connected to both NIBSS and UPSL, so transactions can switch over automatically when one is down. Your provider handles all of this, but it is why your terminal must stay at your registered address.
Data protection registration
In July 2026, Nairametrics reported that the Federal High Court in Lagos (Emmanuel Harunna v. NDPC) had dismissed a challenge to the Nigeria Data Protection Commission’s power to require PoS agents to register as Data Controllers and Processors of Major Importance. The NDPC told unregistered operators to register immediately. Its published fee for the “Ordinary High Level” category is ₦10,000. Check with the NDPC which category applies to your business before you pay.
What you need to start
We have not listed fixed prices for terminals, umbrellas or rent. They vary by provider, city and street, and the only official terminal price list we could find was out of date. Use this checklist to get your own quotes:
| Item | Why you need it | Where to get the real cost |
|---|---|---|
| POS terminal | Usually leased from your principal (often with a caution fee) rather than bought outright | The “Request POS” screen in your provider’s app, or your relationship officer. Ask whether the caution fee is refundable and what happens if you miss transaction targets. |
| Float (working cash and wallet balance) | Cash you pay out for withdrawals, plus the wallet balance you need to accept deposits and transfers | Your own savings. Remember that one customer can only take ₦100,000 a day and your terminal can only pay out ₦1.2 million a day, so you do not need float above that. |
| Business registration | Many principals and banks ask for it, and you need it for a business account and most loans | The CAC portal. The CAC has also run free registration schemes for small businesses (see our guide below). |
| Valid ID, BVN and NIN | Required for KYC by every principal | NIMC and your bank |
| Fixed, visible spot | Geo-fencing means you must operate from one registered address | Landlord or market association. Get the agreement in writing. |
| Power backup and POS paper | A dead terminal or an empty paper roll loses you customers | Local suppliers |
| Lockable cash box and receipt book | For security, and to keep the records the CBN rules require | Local suppliers |
How to register as a POS agent: step by step
- Pick your location first. Geo-fencing ties your terminal to one address, so you cannot just move to a busier spot next month. Spend a weekday and a weekend watching foot traffic, count the agents within a short walk, and check whether nearby ATMs actually pay out cash.
- Register your business name with the CAC. You can do this yourself online. Our guide How to Register a Business with CAC Yourself in 2026 walks you through it, and CAC Business Name Search Nigeria 2026 shows how to check whether a name is taken.
- Choose one principal. This is now a single, binding choice (see the comparison below). Ask agents in your area which network has the least downtime.
- Open the business or agent account and complete KYC. You will need a valid ID, BVN, NIN, proof of address and usually a passport photo. The CBN guidelines bar applicants under 18, people with non-performing loans or criminal records, and anyone with a blacklisted BVN.
- Request your terminal. Use the provider’s app or relationship officer and confirm every fee in writing: caution fee, delivery, insurance and any minimum daily volume.
- Register the exact location. Make sure the GPS coordinates recorded for your terminal match where you will actually sit. A wrong pin can get your terminal blocked once geo-fencing is enforced.
- Put up the required signage. Show your principal’s name, your approved charges and the complaint contact numbers, and give a receipt for every transaction.
- Complete the required training and keep proof that you attended.
- Check your NDPC obligation and register if it applies to you.
Choosing your one provider: what to compare
Moniepoint, OPay and PalmPay have the largest agent networks, and bank programmes such as FirstMonie are also options. Because you can only have one principal, choose carefully. Compare them on these points:
| Question to ask | Why it matters |
|---|---|
| What are the terminal terms (lease or buy, caution fee, refund)? | Some providers lease terminals and can take them back if your volume is low |
| What does the provider charge you per withdrawal and per transfer? | This is deducted before your profit, so get the current schedule from the app |
| How fast is settlement, and what is the reversal process? | Failed transactions that take days to reverse tie up your float and upset customers |
| How reliable is the network on your street? | Ask two or three working agents nearby, because local experience is the best guide |
| Is there a local support officer? | You will need help with geo-fencing, disputes and terminal faults |
| Can you add other services (bill payments, airtime, transfers)? | Extra services earn more from the same customers |
Will your spot make money? A worked example
Earnings depend almost entirely on how many people pass your spot, how many other agents are nearby and what you charge. That is why we do not publish a “typical daily profit” figure. Use this method with your own numbers instead.
Daily profit = (number of transactions × your average charge) − (provider fees + daily share of rent, power, paper, transport to the bank and any loan repayment)
Here is an example with made-up round numbers, just to show the arithmetic. These are not market rates. Suppose you do 40 withdrawals a day, charge an average of ₦X each and pay your provider ₦Y each. Your gross margin is 40 × (X − Y). Take away your daily costs: for example, divide monthly rent by 26 working days and add your daily spend on fuel and paper. Whatever is left is your profit. If it is close to zero or negative, try a different spot or add bill payments and airtime before you put in more float.
Two limits matter here. Because each customer can only take ₦100,000 a day, very large withdrawals have to be spread over several days. And because your terminal stops paying out at ₦1.2 million a day, your daily cash-out volume, and the income that comes from it, has a hard ceiling.
Common problems and how to handle them
Network failures and reversals
Never hand over cash until the terminal shows a successful transaction and prints a receipt. If a customer is debited but the transaction fails, give them your principal’s dispute channel and the receipt reference. Do not settle it from your own pocket.
Fake transfer alerts
Confirm every incoming transfer in your provider’s app, not from an SMS or a screenshot.
Security
Bank your excess cash often, vary the time you go, and do not count large sums in the open. The CBN’s daily cash-out cap means you do not need to keep large cash stocks.
Running out of float
Track your opening and closing cash and wallet balance every day. Most agents run short because cash and wallet balance get out of balance, not because they have too little money in total.
Frequently Asked Questions
Can I use two POS providers in 2026?
No. Under the CBN agent banking guidelines in force since 1 April 2026, an agent can work with only one principal (a bank, microfinance bank, payment service bank, mobile money operator or licensed super agent).
What is the POS withdrawal limit in Nigeria?
₦100,000 per customer per day through POS agents. Customers also have a ₦500,000 weekly cash withdrawal limit across all channels since 1 January 2026. Each agent terminal is capped at ₦1.2 million in cash-outs a day.
What is POS geo-fencing?
Your terminal is linked to the GPS coordinates of your registered business location and only works within 70 metres of it. The CBN widened the radius from 10 metres in a circular dated 29 May 2026, with enforcement from 1 August 2026.
Do I need CAC registration to be a POS agent?
Requirements vary by principal, but the CBN guidelines ask business agents for proof of incorporation and tax compliance. A business name registration also makes it easier to open a business account and get credit, so it is worth doing.
Do POS agents need to register with the NDPC?
The NDPC says yes, and a Federal High Court ruling reported in July 2026 upheld its power to require it. The fee depends on your data-processing category, so confirm yours with the NDPC.
How much does a POS machine cost?
It depends on the provider, and most terminals are now leased with a caution fee rather than sold. Check the current price in your chosen provider’s app before you pay, and ask whether the fee is refundable.
Can I move my POS stand to another street?
Not without your principal’s approval. The guidelines require written notice (usually at least 30 days), and your terminal’s geo-fence must be updated to the new address.
Related reading on NaijaSabi: VTU Business in Nigeria 2026 (add airtime and data sales to your stand) · Free CAC Business Name Registration via SMEDAN · Small Business Ideas Under ₦100,000
Sources
- BusinessDay, “10 things PoS agents need to know under CBN’s new guideline”, 7 October 2025
- TechCabal, “Nigeria’s central bank expands PoS operating radius to 70 metres”, 30 May 2026
- The ICIR, “CBN scraps deposit limits, increases weekly withdrawal threshold”, 3 December 2025
- New Telegraph via NIBSS, “Value of PoS transactions surged 79.03% to N18.78trn in Q1 2026”, 23 April 2026
- Nairametrics, “PoS agents must register with NDPC, court rules”, 28 July 2026
Last updated: 18 October 2026 · NaijaSabi.


0 Comments
No comments yet. Be the first to share your thoughts!