
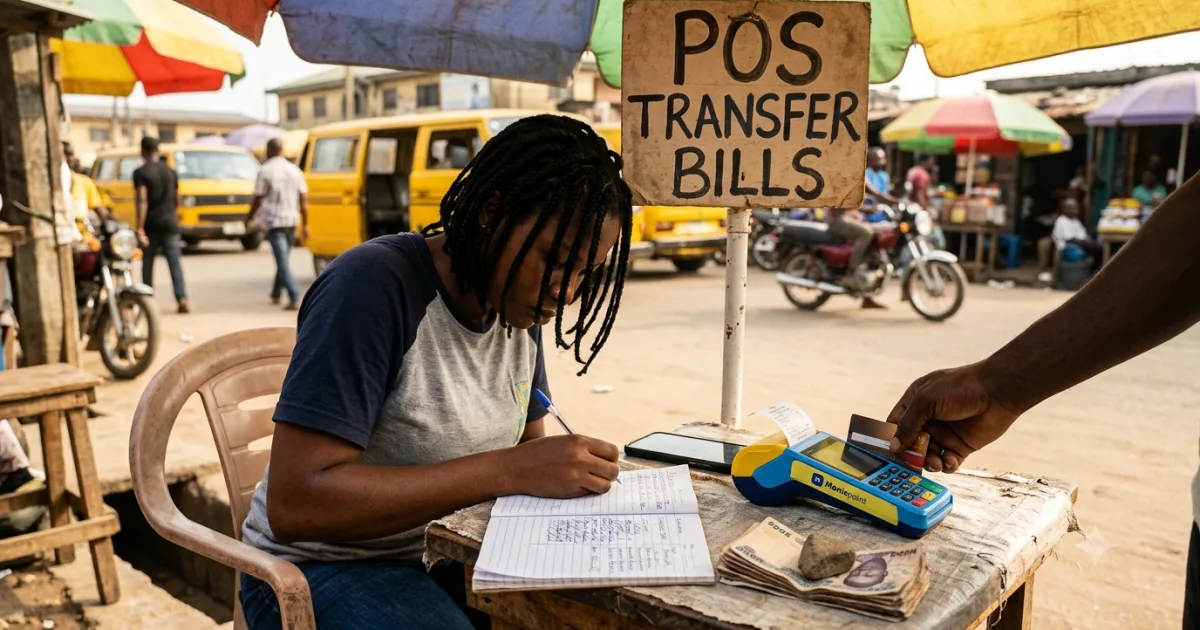
📌 Quick Summary: A POS (Point of Sale) business in Nigeria is an agency banking service where you provide cash withdrawal, deposit, transfer, and bill payment services to customers using a licensed fintech POS machine, earning a commission on every transaction. Startup capital: ₦150,000 to ₦500,000 (machine deposit + working capital). Average daily transactions at a well-located stall: 50 to 150. Average commission per transaction: ₦50 to ₦150. A busy POS stall earns ₦100,000 to ₦400,000 monthly net profit. The three best POS providers in Nigeria in 2026 are Moniepoint, OPay, and PalmPay. This guide covers which provider to choose, how to get a machine, startup costs, commission structures, ideal locations, and common POS business problems.
The POS business is one of Nigeria’s most visible entrepreneurial successes of the past decade. Walk through any Nigerian market, motor park, residential street, or commercial area and you will find POS stalls — often a small table, a machine, and a young person providing banking services to the unbanked and underbanked millions who either do not have bank accounts, cannot reach a bank branch, or find ATMs perpetually empty or out of service. The CBN’s financial inclusion drive, combined with the explosion of fintech platforms like Moniepoint, OPay, and PalmPay, has created a nationwide network of micro-banking agents. For the entrepreneur, it is a business with low entry barriers, immediate cash flow, and the kind of consistent daily demand that comes from a service people need regardless of whether the economy is growing or shrinking. This guide covers exactly how to start, which provider to choose, and what determines whether your POS business thrives or struggles.
How the POS Business Model Works
A POS agent is a licensed representative of a financial institution or fintech company, authorised to perform basic banking transactions on behalf of customers. The business model: the customer brings cash to you for deposit, or asks to withdraw cash; you process the transaction through your POS machine; the fintech company charges the customer a service fee (typically ₦50 to ₦200 per transaction); you receive a percentage of that fee as your commission. The fintech handles the banking infrastructure, fraud protection, and regulatory compliance. You provide the physical presence, the cash float, and the customer service. Your income is the accumulated commission from every transaction you process each day.
The Three Best POS Providers in Nigeria 2026
| Provider | Machine Cost/Deposit | Commission Per Withdrawal | Commission Per Transfer | Minimum Float Required | Best For |
| Moniepoint | ₦35,000 deposit (refundable) | 0.5% of transaction value (min ₦50, max ₦500) | ₦20 – ₦50 per transfer | ₦100,000 – ₦500,000 | High-volume commercial locations; markets; motor parks. Most widely used POS in Nigeria. |
| OPay | ₦20,000 – ₦35,000 (machine purchase) | 0.5% of transaction value | ₦15 – ₦40 per transfer | ₦100,000 – ₦300,000 | Urban areas; Lagos; mixed-use residential/commercial locations |
| PalmPay | ₦30,000 (deposit) | 0.5% of transaction value | ₦15 – ₦50 per transfer | ₦100,000 – ₦300,000 | Newer entrant; aggressive commission structure; good in areas with younger smartphone-savvy customers |
| Firstmonie (First Bank) | Free (bank customer requirement) | Bank-determined commission structure | Bank-determined | ₦50,000+ | Existing First Bank customers wanting agent banking extension |
| GTBank Xtra | Free (GTBank customer requirement) | Bank-determined | Bank-determined | ₦50,000+ | Existing GTBank customers |
The 2026 recommendation: Start with Moniepoint. It has the largest agent network in Nigeria, the most reliable uptime, the most comprehensive transaction types (cash in, cash out, transfers, airtime, utility bills), and the strongest brand recognition among Nigerian customers who actively look for Moniepoint agents. OPay is a strong second choice, particularly in Lagos.
How to Get a Moniepoint POS Machine
- Download the Moniepoint Business app from Google Play Store or Apple App Store.
- Register as a business: provide your BVN, NIN, a valid Nigerian ID, and a utility bill for your business address.
- Complete KYC (Know Your Customer) verification — Moniepoint’s team will review and approve your application, typically within 2 to 5 business days.
- Pay the refundable machine deposit (₦35,000 as at September 2026 — confirm current amount in the app).
- Receive your terminal — delivered to your registered address or collected from a Moniepoint hub in your state.
- Fund your Moniepoint business account — this is your float, the working capital you use for cash withdrawals. The more float you maintain, the more transactions you can process daily.
Startup Capital: Full Breakdown
| Item | Cost |
| POS machine deposit (Moniepoint) | ₦35,000 |
| Working capital float (minimum recommended) | ₦150,000 – ₦300,000 |
| Small table or kiosk setup | ₦5,000 – ₦30,000 |
| Chair, umbrella/canopy (for outdoor stalls) | ₦10,000 – ₦20,000 |
| Phone for the POS app (if you do not have one) | ₦30,000 – ₦80,000 |
| Receipt paper rolls (2 months supply) | ₦3,000 – ₦5,000 |
| Minimum to start (shared kiosk/table) | ₦203,000 – ₦370,000 |
| Comfortable startup capital | ₦400,000 – ₦600,000 |
How Much Does a POS Business Make?
| Location Type | Daily Transactions | Avg Commission per Transaction | Daily Gross Earnings | Monthly Gross (25 days) |
| Quiet residential street | 20 – 40 | ₦70 | ₦1,400 – ₦2,800 | ₦35,000 – ₦70,000 |
| Busy market or bus stop | 80 – 150 | ₦80 | ₦6,400 – ₦12,000 | ₦160,000 – ₦300,000 |
| Motor park or transport hub | 120 – 200 | ₦90 | ₦10,800 – ₦18,000 | ₦270,000 – ₦450,000 |
| Area with no nearby ATM or bank | 100 – 180 | ₦100 | ₦10,000 – ₦18,000 | ₦250,000 – ₦450,000 |
The Single Most Important Factor: Location
Location determines 70 percent of POS business success. The ideal POS location has four characteristics. First: high foot traffic — markets, bus stops, motor parks, school areas, hospital gates, church exits, and commercial streets generate more transactions per hour than residential areas. Second: underserved banking access — areas where the nearest bank branch or ATM is more than 500 metres away generate higher transaction volumes because you are solving a genuine access problem, not just a convenience. Third: a large unbanked or cash-dependent population — artisans, traders, market sellers, transportation workers, and daily wage earners in these areas transact in cash constantly and need POS services multiple times per week. Fourth: manageable competition — opening a POS stall directly beside three existing POS stalls splits the available transactions four ways. Survey the location for one full working day before committing — count transactions at existing POS stalls if present, and estimate whether the foot traffic volume can support an additional agent.
Managing Your Float: The Cash Management Challenge
Your float — the cash in your machine’s linked account and the physical cash at your stall — determines how many transactions you can process. Running out of cash mid-day means turning away customers and losing income. The float management discipline that separates profitable POS businesses from struggling ones: never spend your float on personal expenses; reconcile your float at the end of every working day; maintain a minimum float that covers your typical daily withdrawal volume plus 30 percent buffer; if your float runs low during a busy day, use mobile transfer between your bank account and your Moniepoint wallet to top up immediately. Float security is also a real concern — keep most of your cash out of sight, do not display large amounts of naira publicly, and consider a small cash safe or lockbox at your stall.
Common POS Business Problems and Solutions
| Problem | Cause | Solution |
| Transaction declined but customer charged | Network timeout — transaction failed after debit | Do not give cash immediately. Check your Moniepoint app for confirmation. If customer was debited but you received nothing, raise a dispute through the Moniepoint app immediately — funds are typically reversed within 24 to 72 hours. |
| Machine offline | Network outage or app issue | Check your internet connection (switch data networks — Airtel to MTN). Force close and reopen the app. If still offline, contact Moniepoint support at 018882188. |
| Low float — can’t process large withdrawals | Float depleted | Transfer funds from your bank account to your Moniepoint wallet via the app immediately. Maintain a ₦150,000 minimum float at all times for a busy stall. |
| Fraudulent customer reversal attempts | Customer claims they did not receive cash after you paid | Always take a photo or video of cash handover for large transactions. Moniepoint’s dispute resolution process reviews transaction logs — documented cash handover protects you. |
Frequently Asked Questions
How much do I need to start a POS business in Nigeria?
Minimum ₦200,000 to ₦400,000 — covering the machine deposit (₦35,000 for Moniepoint), a working capital float of ₦150,000 to ₦300,000, and basic stall setup costs. The float is the most important component — more float means more transactions processed daily.
Which POS machine is best in Nigeria 2026?
Moniepoint is the most widely recommended for new POS agents in 2026 — best uptime reliability, largest customer recognition, most transaction types supported. OPay is a strong alternative particularly in Lagos.
How much does a POS business make per day in Nigeria?
A busy, well-located POS stall processes 80 to 150 transactions daily, earning ₦5,000 to ₦15,000 in commissions. A quiet residential stall earns ₦1,500 to ₦3,000 daily. Location is the primary determinant of transaction volume.
Do I need a CAC registration to operate a POS business?
For sole operator POS agency banking, formal CAC business registration is not typically required to obtain a Moniepoint or OPay machine. However, CAC registration enables higher transaction limits, better dispute resolution standing, and positions the business for growth. If you plan to operate multiple POS terminals, CAC registration becomes important.
Running a POS Business Safely in Nigeria
Security is the most serious operational concern for Nigerian POS operators — cash businesses attract theft and fraud. Practical security measures that experienced POS operators use consistently. Never display large amounts of cash openly — when counting cash for a customer, do so discreetly and keep excess float out of sight. Avoid conducting very large transactions (above ₦200,000) at outdoor stalls — request customers for very large withdrawals to come during early morning or late evening when foot traffic is lower and transactions are more private. Know your regular customers — familiarity with your customer base helps identify strangers attempting to use fraudulent accounts or fake debit cards. Limit your operating hours to daylight — POS stalls that operate after dark face higher robbery risk than those that close at sunset. Build a relationship with nearby commercial bank branches — they can provide large cash top-ups when your float runs low and often alert agents to circulating counterfeit notes. Register your POS business details with your local vigilante group or community security association — community awareness of your business location and operating hours provides informal security coverage that formal security rarely matches in Nigerian informal economy settings.
Sources
- CBN Agent Banking Guidelines — cbn.gov.ng
- Moniepoint official agent terms and commission structure — moniepoint.com — September 2026
- Original business guide — NaijaSabi Business Desk, September 2026
Last updated: 16 September 2026 · NaijaSabi Business Desk. Commission rates and machine costs reflect provider terms as at September 2026 and are subject to change.
Scaling Your POS Business: From One Terminal to Multiple
The natural growth path for a successful POS business is adding terminals and locations. A single well-located terminal earning ₦200,000 monthly net profit is a good business. Three terminals in three different high-traffic locations earning ₦150,000 each is a ₦450,000 monthly business that is far more resilient — if one location has a slow week, the others compensate. The path from one terminal to multiple: operate your first terminal for a minimum of 3 months to establish consistent transaction volume and understand the cash flow dynamics. Use profits to fund the float for a second terminal rather than taking on personal debt. Hire a trusted agent (a reliable young person in your network) to operate the second terminal, paying a fixed daily wage or commission split. Most multi-terminal POS operators in Nigeria pay agents ₦3,000 to ₦5,000 per day or 30 to 40 percent of daily commissions — both models work depending on transaction volume. By month 6 with two profitable terminals, the third becomes self-funding from accumulated profits. Nigerian POS entrepreneurs who have scaled to 10 or more terminals are running genuine financial services businesses — managing float across multiple locations, employing multiple agents, and earning ₦1,000,000 to ₦3,000,000 monthly net profit from an initial investment of ₦400,000 to ₦600,000. The model scales because the core product — cash access and basic banking — has unlimited demand in Nigeria’s predominantly cash-based informal economy.

0 Comments
No comments yet. Be the first to share your thoughts!