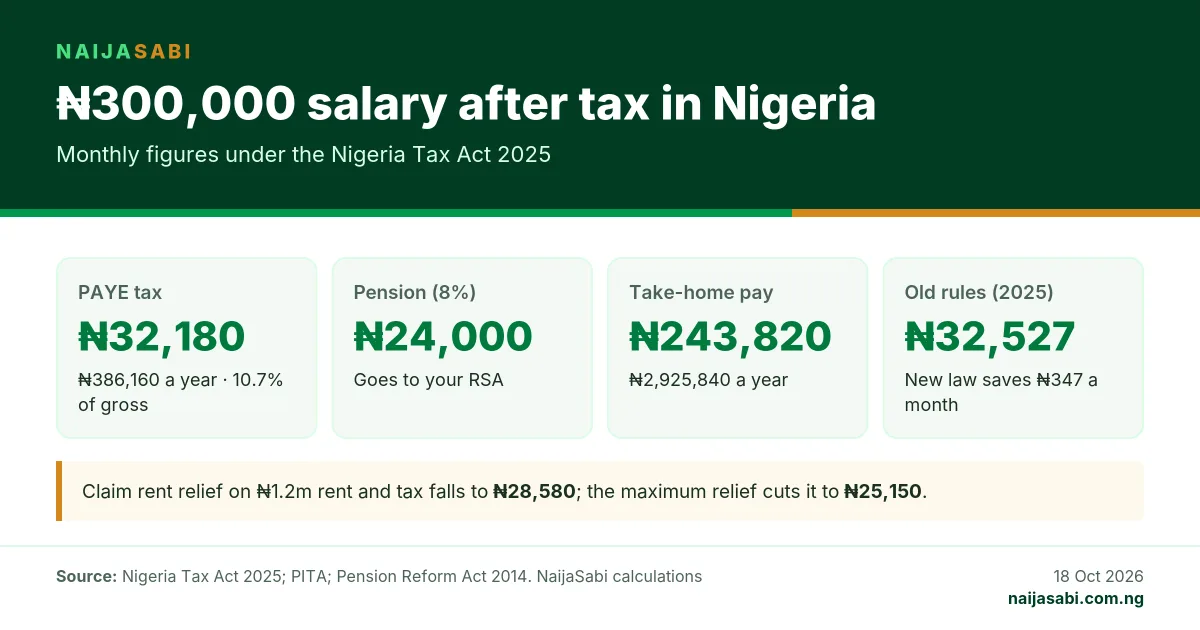
📌 Quick answer: On a gross salary of ₦300,000 a month in 2026, you pay ₦32,180 PAYE tax and ₦24,000 pension (8%), so your take-home pay is ₦243,820, an effective tax rate of 10.7%. That is ₦347 a month less tax than under the old rules. At this salary part of your income is now taxed at 18%, which makes rent relief worth more: on ₦1.2 million rent your tax falls to ₦28,580, and the maximum relief cuts it to ₦25,150.
₦300,000 a month is a common salary for experienced professionals, team leads, senior analysts, engineers and specialists, especially in Lagos, Abuja and Port Harcourt. Since 1 January 2026, PAYE on that pay has been worked out under the Nigeria Tax Act 2025. The Act replaced the old Consolidated Relief Allowance with a tax-free first ₦800,000 a year and introduced new reliefs, including rent relief.
₦300,000 is also an important line in the new system. It is just above the point where the 18% band begins, so the calculation has one more step than at lower salaries. Here it is in full.
₦300,000 Salary After Tax: The Full Breakdown
| Item | Monthly | Yearly |
|---|---|---|
| Gross salary | ₦300,000 | ₦3,600,000 |
| Pension (8% employee contribution) | −₦24,000 | −₦288,000 |
| Chargeable income | ₦276,000 | ₦3,312,000 |
| Taxed at 0% (first ₦800,000 a year) | ₦66,667 | ₦800,000 |
| Taxed at 15% (next ₦2,200,000) | ₦183,333 | ₦2,200,000 |
| Taxed at 18% (the rest) | ₦26,000 | ₦312,000 |
| PAYE tax | −₦32,180 | −₦386,160 |
| Take-home pay | ₦243,820 | ₦2,925,840 |
How the ₦32,180 Is Worked Out
- Yearly gross pay: ₦300,000 × 12 = ₦3,600,000.
- Take off pension: 8% of ₦3,600,000 is ₦288,000, leaving a chargeable income of ₦3,312,000.
- First band: the first ₦800,000 is taxed at 0%.
- Second band: the next ₦2,200,000 is taxed at 15% = ₦330,000.
- Third band: the remaining ₦312,000 is taxed at 18% = ₦56,160.
- Tax for the year: ₦330,000 + ₦56,160 = ₦386,160.
- Monthly PAYE: ₦386,160 ÷ 12 = ₦32,180.
Take-home pay is ₦300,000 − ₦24,000 − ₦32,180 = ₦243,820. The 18% band starts once chargeable income passes ₦3 million a year. With 8% pension on the full salary, that happens at a gross salary of about ₦271,700 a month. Only the part of your pay above that line is taxed at 18%; the rest is still taxed at 0% and 15%.
Old Rules vs New Rules at ₦300,000
| ₦300,000 a month | 2025 (old PITA rules) | 2026 (Nigeria Tax Act 2025) |
|---|---|---|
| Reliefs | Pension + CRA of ₦920,000 a year | Pension; first ₦800,000 taxed at 0% |
| Chargeable income (yearly) | ₦2,392,000 | ₦3,312,000 |
| Tax for the year | ₦390,320 | ₦386,160 |
| Monthly PAYE, no rent relief | ₦32,526.67 | ₦32,180 |
| Difference | New law saves ₦346.67 a month (₦4,160 a year) | |
| Monthly PAYE with ₦1.2m rent relief | ₦32,526.67 (no rent relief existed) | ₦28,580, saving ₦3,946.67 a month |
The saving without reliefs is small, about ₦350 a month. The old Consolidated Relief Allowance grew with your pay (₦200,000 plus 20% of gross), and at ₦300,000 a month it was worth ₦920,000 a year, more than the new ₦800,000 tax-free band. The new law still comes out slightly ahead here because its 15% band is so wide: under the old rules, much of a ₦300,000 earner’s income was taxed at 19% and 21%.
That balance does not hold at every salary. Our calculations, with 8% pension and no other reliefs, show the new law costs slightly more between about ₦150,000 and ₦215,000 a month (by at most about ₦83) and again between about ₦325,000 and ₦532,000 a month (by up to about ₦1,000, at around ₦393,500). Salaries above about ₦1.28 million a month also pay more without reliefs. If you are close to one of those ranges, rent relief and other reliefs decide whether you gain. See our breakdowns for ₦150,000 and ₦200,000.
What Changes Your Number
| Your situation (₦300,000 gross) | Monthly tax | Monthly take-home |
|---|---|---|
| Standard: 8% pension on the full ₦300,000 | ₦32,180 | ₦243,820 |
| You pay ₦75,000 a month rent (₦900,000 a year) and claim rent relief | ₦29,480 | ₦246,520 |
| You pay ₦100,000 a month rent (₦1.2m a year) and claim rent relief | ₦28,580 | ₦247,420 |
| You pay ₦150,000 a month rent (₦1.8m a year) and claim rent relief | ₦26,900 | ₦249,100 |
| Your rent is ₦2.5m a year or more (maximum relief of ₦500,000) | ₦25,150 | ₦250,850 |
| Your employer deducts NHF on a ₦150,000 basic salary (₦3,750) | ₦31,505 | ₦240,745 |
| Pension is on basic + housing + transport of ₦210,000 only (₦16,800) | ₦33,476 | ₦249,724 |
| Your employer runs no pension scheme | ₦36,500 | ₦263,500 |
Rent relief is worth more at ₦300,000
You can deduct 20% of the rent you pay in a year, up to ₦500,000, before tax is worked out. At lower salaries every ₦100,000 of relief saves ₦15,000 a year. At ₦300,000 the relief first comes off income taxed at 18%, so the first ₦312,000 of relief saves ₦18,000 for every ₦100,000, and anything beyond that saves ₦15,000.
- ₦1.2 million rent: relief of ₦240,000, all at 18%, saves ₦43,200 a year (₦3,600 a month).
- ₦2.5 million rent or more: the maximum relief of ₦500,000 saves ₦84,360 a year (₦7,030 a month).
Payroll can only apply it if HR knows. Tell them what you pay, and keep your tenancy agreement and rent receipts, which your employer may ask for. If you live in your own house, a family house or staff quarters, there is no rent relief to claim.
Pensionable pay
Under the Pension Reform Act 2014, your 8% is based on basic salary, housing and transport. Many ₦300,000 packages include other allowances, such as utility, meal or leave allowances, so the pension deduction can be lower than ₦24,000. That raises your tax a little but leaves more cash in hand, as the table shows. Your employer adds at least 10% of the same amount into your Retirement Savings Account; that is not taken from your salary.
Salaries Close to ₦300,000
| Gross monthly salary | 2026 PAYE | 2026 take-home | 2025 PAYE (old rules) |
|---|---|---|---|
| ₦250,000 | ₦24,500 | ₦205,500 | ₦24,967 |
| ₦275,000 | ₦28,040 | ₦224,960 | ₦28,747 |
| ₦300,000 | ₦32,180 | ₦243,820 | ₦32,527 |
| ₦320,000 | ₦35,492 | ₦258,908 | ₦35,551 |
| ₦350,000 | ₦40,460 | ₦281,540 | ₦40,087 |
| ₦400,000 | ₦48,740 | ₦319,260 | ₦47,787 |
Above about ₦271,700 a month, every extra ₦10,000 of gross pay adds ₦1,656 in PAYE and ₦800 in pension, so you keep ₦7,544 of it. Below that line you keep ₦7,820 of each ₦10,000. That is worth knowing when you weigh a pay rise or a job offer: the difference is real, but small.
Work Out Your Own Take-Home Pay
Enter your own salary, rent, NHF and allowances below. The calculator uses the 2026 rules and shows the old-rules figure for comparison.
Take-home pay calculator 2026
Nigeria Tax Act 2025 rates, in force since 1 January 2026.
| Monthly | Yearly |
|---|
How your tax was worked out
What it costs your employer
Take-home on common salaries
| Gross a month | Tax a month | Take-home a month |
|---|---|---|
| ₦70,000 | ₦0 | ₦64,400 |
| ₦100,000 | ₦3,800 | ₦88,200 |
| ₦150,000 | ₦10,700 | ₦127,300 |
| ₦250,000 | ₦24,500 | ₦205,500 |
| ₦500,000 | ₦65,300 | ₦394,700 |
| ₦1,000,000 | ₦148,100 | ₦771,900 |
With 8% pension on the full gross pay, no NHF and no rent relief.
An estimate. Your employer's payroll may treat allowances differently. For a formal answer ask your HR team or a tax adviser.
Source: Nigeria Tax Act 2025 (sections 30 and 58, Fourth Schedule); Pension Reform Act 2014; National Housing Fund Act; National Minimum Wage (Amendment) Act 2024. Employer costs: Pension Reform Act 2014 (at least 10%), Employee's Compensation Act 2010 (NSITF, 1%), Industrial Training Fund Act (ITF, 1%).
Check Your Payslip
- Tax above ₦32,180 on ₦300,000? If you have no other income and your pension is on the full gross, ask HR how it was worked out. A smaller pensionable base (see the table above) is the most common reason.
- Paying rent but tax unchanged? Rent relief has not been applied. Give HR your rent details and documents.
- Pension deducted but missing from your RSA? Compare your payslip with your Retirement Savings Account statement from your Pension Fund Administrator.
- PAYE goes to your state. Salary tax is paid to the tax authority of the state where you live.
Frequently Asked Questions
How much tax is paid on ₦300,000 salary in Nigeria in 2026?
₦32,180 a month (₦386,160 a year), with 8% pension on the full salary and no other reliefs.
What is ₦300,000 a month after tax?
₦243,820 a month, or ₦2,925,840 a year, after ₦32,180 tax and ₦24,000 pension.
Do I pay less tax on ₦300,000 under the new law?
Yes, slightly: ₦346.67 a month less than under the old rules without any reliefs. With rent relief on ₦1.2 million rent, you pay ₦3,946.67 a month less than before.
Am I in the 18% tax band on ₦300,000?
Partly. Only ₦312,000 of your yearly chargeable income, the part above ₦3 million, is taxed at 18%. The first ₦800,000 is taxed at 0% and the next ₦2.2 million at 15%.
What is the effective tax rate on ₦300,000?
About 10.7% of gross pay, with pension as the only relief.
Sources
- Nigeria Tax Act 2025 – income tax bands (Fourth Schedule) and allowable reliefs including rent relief (section 30), in force from 1 January 2026
- Personal Income Tax Act (as amended) – Consolidated Relief Allowance and tax bands applying until 31 December 2025
- Pension Reform Act 2014 – employee (8%) and employer (10%) contributions on basic salary, housing and transport allowances
Last updated: 23 October 2026 · NaijaSabi Finance Desk. Figures are worked examples for a single source of employment income; your payslip can differ if you have other income, allowances or reliefs. This is general information, not tax advice.

0 Comments
No comments yet. Be the first to share your thoughts!