


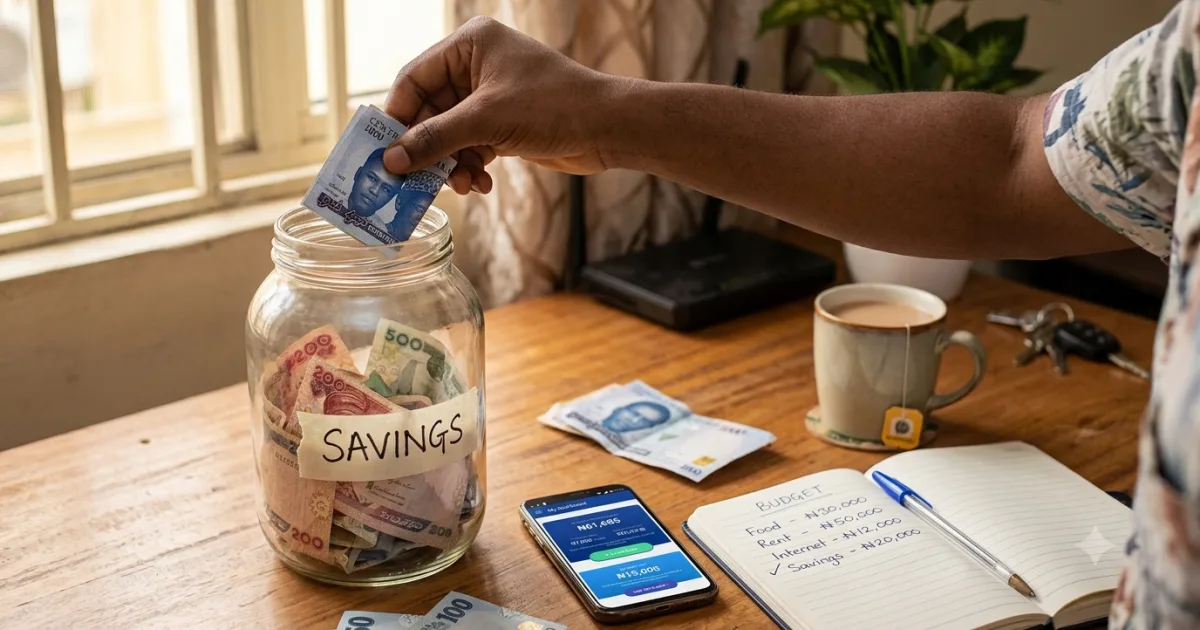
📌 Quick Summary: Saving money in Nigeria in 2026 requires a system — not willpower. The most effective Nigerian savings approach combines: Pay Yourself First (transfer a fixed amount to savings on the same day your salary arrives, before any spending), a high-yield savings account (money market funds at 20 to 28% annual interest are available from PiggyVest, Cowrywise, ARM, and others), and a written monthly budget. A Nigerian earning ₦150,000 monthly who saves just 10% (₦15,000) in a money market fund earning 24% per year will have accumulated approximately ₦237,000 after 12 months — ₦37,000 more than the ₦200,000 they saved directly, just from interest. This guide covers exactly how to start, which savings product to use at every income level, how to save on a low salary, and the most common Nigerian savings mistakes.
The most common reason Nigerians give for not saving money is that there is nothing left to save after monthly expenses. This is frequently true as a description of what happens — but it is not true as a structural reality. The pattern of spending first and saving whatever remains guarantees that nothing remains to save, because expenses expand to fill available income. The solution is a system, not a resolution. This guide provides the system — specific, practical, and designed for the realities of Nigerian income patterns, banking infrastructure, and the economic environment of 2026.
Why Saving Money in Nigeria Is Harder Than in Other Countries
Nigerian savings face three structural challenges that most personal finance guides written for Western audiences do not address. First: inflation. Nigeria’s inflation rate in 2026 — while lower than its 2024 peak — remains above 25 percent annually. This means money sitting in a standard Nigerian bank savings account at 2 to 4% interest is losing purchasing power in real terms every month. Saving in Nigeria requires saving in instruments that outrun inflation — which means moving beyond the basic savings account. Second: irregular income. Many Nigerians — particularly those in the informal economy, freelancers, small business owners, and contractors — do not receive a fixed monthly salary on a predictable date. Savings systems built on fixed monthly transfers from salary break down when income is irregular. Third: social financial pressure. Nigerian social culture involves significant financial obligations — aso-ebi contributions, owambe attendance, family emergency support, church and mosque tithing, and the expectation of financial generosity that can rapidly drain savings built up over months. A savings plan that does not account for these obligations will fail when they arrive — and they always arrive.
The Pay Yourself First Principle: The Single Most Important Savings Habit
Pay Yourself First means transferring your savings amount before paying any expense — on the same day your income arrives. Not at the end of the month when you see what is left (there will be nothing left). On the day the money enters your account, the first transaction is a transfer to your savings. This is the foundational principle of savings psychology and it works for one simple reason: the money you have transferred to savings before paying expenses does not feel like money you have. Your brain adapts to the available balance remaining after the savings transfer. You make spending decisions based on what you have — not what you used to have before the transfer. Most Nigerians who have successfully built savings over multiple years cite Pay Yourself First as the specific habit that made the difference. Not a change in income. Not a change in expenses. The single change of timing — savings first, spending second.
How Much Should You Save? The Nigerian Guide
| Monthly Income | Recommended Savings Rate | Monthly Savings Amount | Reality Check |
| Below ₦80,000 | 5% — even ₦4,000 per month builds a habit | ₦4,000 – ₦4,000 | At this income level, the habit matters more than the amount |
| ₦80,000 – ₦150,000 | 10% | ₦8,000 – ₦15,000 | This builds approximately ₦100,000 to ₦200,000 per year before interest |
| ₦150,000 – ₦300,000 | 15% | ₦22,500 – ₦45,000 | This is where a meaningful emergency fund starts to develop within 6 months |
| ₦300,000 – ₦600,000 | 20% | ₦60,000 – ₦120,000 | At this level, an emergency fund plus investment savings becomes achievable simultaneously |
| Above ₦600,000 | 25 to 30% | ₦150,000+ | Multiple savings goals become achievable — emergency fund, investment, housing goal |
Where to Keep Your Savings in Nigeria 2026
| Product | Interest Rate (2026) | Liquidity | Best For | Provider |
| Standard bank savings account | 2 – 4% per year | Instant | Operating emergency fund only | All Nigerian commercial banks |
| PiggyVest Flex savings | 10 – 13% per year | Instant withdrawal | Short-term savings goals (under 3 months) | PiggyVest |
| PiggyVest SafeLock | 13 – 17% per year | Locked until target date | Savings goals where discipline is needed | PiggyVest |
| Money market funds (ARM, Stanbic, United Capital) | 20 – 28% per year | T+1 to T+3 (1 to 3 business days) | Main savings — best balance of return and liquidity | ARM Money Market, Stanbic IBTC, United Capital |
| Cowrywise Plans | 14 – 20% per year | Locked until plan target | Specific savings goals — housing deposit, education, car | Cowrywise |
| Nigerian Treasury Bills | 18 – 24% per year | 91, 182, or 364-day terms | Medium-term savings for amounts above ₦50,000 | Stockbrokers, CBN portal |
| Dollar savings (domiciliary account) | 0.5 – 2% in USD terms | Instant | Hedge against naira depreciation | GTBank, Access, Zenith dom account |
The 2026 recommendation for most Nigerians: Keep 1 to 2 months of expenses in a standard savings account for immediate emergencies. Put all other savings in a money market fund (ARM, Stanbic, or United Capital) earning 20 to 28% per year. This approach outpaces inflation and keeps your savings growing in real terms while remaining accessible within 1 to 3 business days when genuinely needed.
How to Save Money on a Low Salary in Nigeria
Saving on a low salary is not about finding more money to save — it is about making saving automatic before spending begins, finding one specific expense to reduce (not everything at once), and accepting that the first few months the amount will be small. The three lowest-effort interventions for Nigerians earning below ₦150,000 monthly. First: start a ajo or esusu with 5 to 10 trusted people. Rotating savings groups — where each member contributes a fixed amount monthly and receives the full pot in rotation — have helped Nigerians save for generations. The social accountability of the group enforces saving discipline that individual savings accounts often cannot. Second: use PiggyVest’s Autosave feature to automatically deduct a small amount (even ₦500 to ₦1,000 per day) from your bank account. Small daily amounts accumulate without feeling significant. Third: identify the one largest discretionary expense in your current lifestyle and reduce it by 30 percent. Not eliminate — reduce. For most Nigerians in this income bracket, transport, eating out, and airtime/data are the three largest controllable expenses.
Saving for Specific Nigerian Goals
Generic savings advice tells you to save — Nigerian-specific advice tells you what for and how long. Three of the most common Nigerian savings goals and the recommended approach for each. Building an emergency fund: target 3 months of essential expenses (rent, food, transport, utilities). Keep this in a money market fund — accessible but separated from your spending account so you are not tempted. A ₦150,000/month earner needs approximately ₦450,000 in emergency reserves. At a savings rate of 15% (₦22,500/month), this takes 20 months to build from scratch. Saving for rent (advance): Nigerian landlords typically demand 1 to 2 years of rent in advance — a major barrier for most Nigerians. A dedicated Cowrywise or PiggyVest plan with a specific rent-advance target and date gives you a locked savings account that builds toward this goal without the temptation to dip into it. Saving for japa (relocation abroad): visa fees, flight tickets, and the initial settling-in costs of relocating to the UK, Canada, or Europe typically require ₦2,000,000 to ₦5,000,000 in liquid savings. A dedicated 24 to 36 month savings plan at ₦80,000 to ₦150,000 per month in a money market fund is the realistic pathway for a middle-income Nigerian professional targeting international relocation.
Frequently Asked Questions
How much should I save from my salary in Nigeria?
10 to 20 percent of your monthly income is the standard recommendation. If 20 percent feels impossible, start with 5 percent and increase by 2 percent every 3 months. The amount matters less than starting the habit immediately and making it automatic through Pay Yourself First.
What is the best savings app in Nigeria in 2026?
For most Nigerians, PiggyVest offers the best combination of ease of use, flexible and locked savings options, and competitive interest rates (10 to 17% per year). For higher returns with slightly less liquidity, money market funds through ARM Invest or Stanbic IBTC offer 20 to 28% per year.
How do I save money when my salary is very small?
Start with an amount so small it is impossible to justify not saving — ₦500 per day automatically deducted through PiggyVest Autosave, or ₦2,000 per week transferred manually every Monday before any other spending. The amount is less important than the habit of saving before spending.
Is it better to save in naira or dollars in Nigeria?
For money you will spend in Nigeria within 12 months, naira money market funds (20 to 28% interest) outperform dollar savings (0.5 to 2% in USD terms) even accounting for naira depreciation risk in most market conditions. For money you plan to spend abroad, or as a long-term hedge against severe naira depreciation, maintaining a dollar savings account alongside your naira money market fund is the balanced approach most Nigerian financial advisers recommend in 2026.
Sources
- CBN Money Market Fund data — cbn.gov.ng — 2026 interest rate environment
- PiggyVest, Cowrywise, ARM Invest — official savings product rates — September 2026
- Original financial guide — NaijaSabi Finance Desk, September 2026
Last updated: 14 September 2026 · NaijaSabi Finance Desk. Interest rates are indicative based on September 2026 market rates and are subject to change. This guide is for general financial information and does not constitute financial advice. Consult a qualified financial adviser for personalised guidance.
The Ajo and Esusu: Nigeria’s Traditional Savings Wisdom
Long before PiggyVest and money market funds existed, Nigerians had ajo (Yoruba) and esusu (Igbo) — rotating savings groups that have functioned as informal savings and credit systems across West Africa for centuries. The mechanism is simple: a group of 10 to 20 trusted people each contribute a fixed amount monthly (say ₦20,000 each), and each month one member receives the full pot (₦200,000 for a 10-person group). Over 10 months, each member has contributed ₦200,000 and received ₦200,000 — no interest earned or paid, but each member has had access to ₦200,000 in a single month that would have taken 10 months to accumulate individually. The psychological advantage of ajo and esusu over individual savings is significant: the social obligation to the group enforces contributions that individual discipline might not. Missing your ajo contribution is a social event — it affects your relationships and reputation — in a way that missing a transfer to your own PiggyVest account is not. For Nigerians who struggle with individual savings discipline, ajo or esusu with trusted friends, family, or colleagues remains one of the most effective savings mechanisms available — fully free, requiring no app or account, and carrying the same centuries-old social infrastructure that has made it work across generations. The limitation: ajo and esusu require complete trust in all group members. Financial disputes within ajo groups are one of the most common sources of conflict among Nigerian friends and family. Choose your ajo members with the same care you would choose a business partner.
What Not to Do: The Most Expensive Nigerian Savings Mistakes
Three mistakes consistently prevent Nigerian savings from growing. First: keeping savings in a standard bank savings account earning 2 to 4% while inflation runs at 25 to 30% is not savings — it is slow-motion loss of purchasing power. Every month your money sits in a 3% savings account during 25% inflation, it loses approximately 2% of its real value. After 12 months, ₦100,000 in a 3% savings account is worth approximately ₦78,000 in 2024 purchasing power. Move savings above your immediate emergency fund into money market funds or treasury bills. Second: dipping into savings for non-emergencies. Every withdrawal from savings that is not a genuine emergency — a clothing purchase, a social event contribution, a phone upgrade — resets the compounding clock and erodes the psychological sense of progress that keeps saving motivation strong. The solution is a second account specifically labelled for emergencies that you genuinely do not touch for lifestyle expenses. Third: not starting because the amount feels too small. Nigerians who wait until they can save ₦50,000 per month before starting often wait years. The person who starts saving ₦5,000 per month today and the person who starts saving ₦50,000 per month in two years will have very different financial positions in five years — and it will not be because of the difference in amounts.

0 Comments
No comments yet. Be the first to share your thoughts!